


There are countless internet articles with idealized definitions of how to start your own business.
Many people picture themselves as a forward-thinking individual who has made a major impact in the world, while sitting in their favorite coffee shop, and with absolutely no formal training on how to run a successful company.
However, this does not accurately describe what entrepreneurship actually means.
Nor does it reflect the reality of starting and operating a business.
For starters, entrepreneurship is not a characteristic of an individual, but rather it is a process of doing business.
In short, entrepreneurship is taking a problem, designing a solution, and then convincing other people to pay for that solution.
Unfortunately, while many beginner’s guides reference and describe the psychology of an entrepreneur (resilience, passion, etc.), these traits have nothing to do with the process of entrepreneurship in and of itself.
You cannot purchase a URL by being passionate about your idea. You cannot file taxes by being resilient. And you cannot convince a buyer to purchase your product with passion alone.
In order to develop a successful business concept, an entrepreneur must look beyond textbook definitions of entrepreneurship.
They must examine the process of validating their idea, the legal construction of their company, and the daily management of cash flow.
This guide cuts through the fluff and presents a straightforward explanation of how an entrepreneur can obtain an idea and put that idea into action to become successful.
Bottom line – The truth about starting a business
In case you don’t have time to read the entire article, we will provide you with a summary of the main points below.
In summary, launching a venture is all about being able to validate your concept first and foremost.
You cannot create a business plan if you have only had conversations with non-paying customers about your business idea.
If you think about the validation of your business idea first, you will then have the ability to build a successful company.
Secondly, when developing your business idea, the cash constraints that you will experience will force you to think and be creative.
Large investment rounds can create the illusion that something is inherently valuable because of the amount of capital that was invested in it.
Another important consideration is how to handle the legal and operational "plumbing."
When someone combines their personal finances with their business finances, it is only a matter of time before that person will face an administrative mess.
Lastly, no one cares about what you have created until they feel connected to an issue that they are currently facing. Connecting those two concepts is your responsibility.
What is entrepreneurship?
To better understand how entrepreneurship operates, we first need to agree upon a common definition.
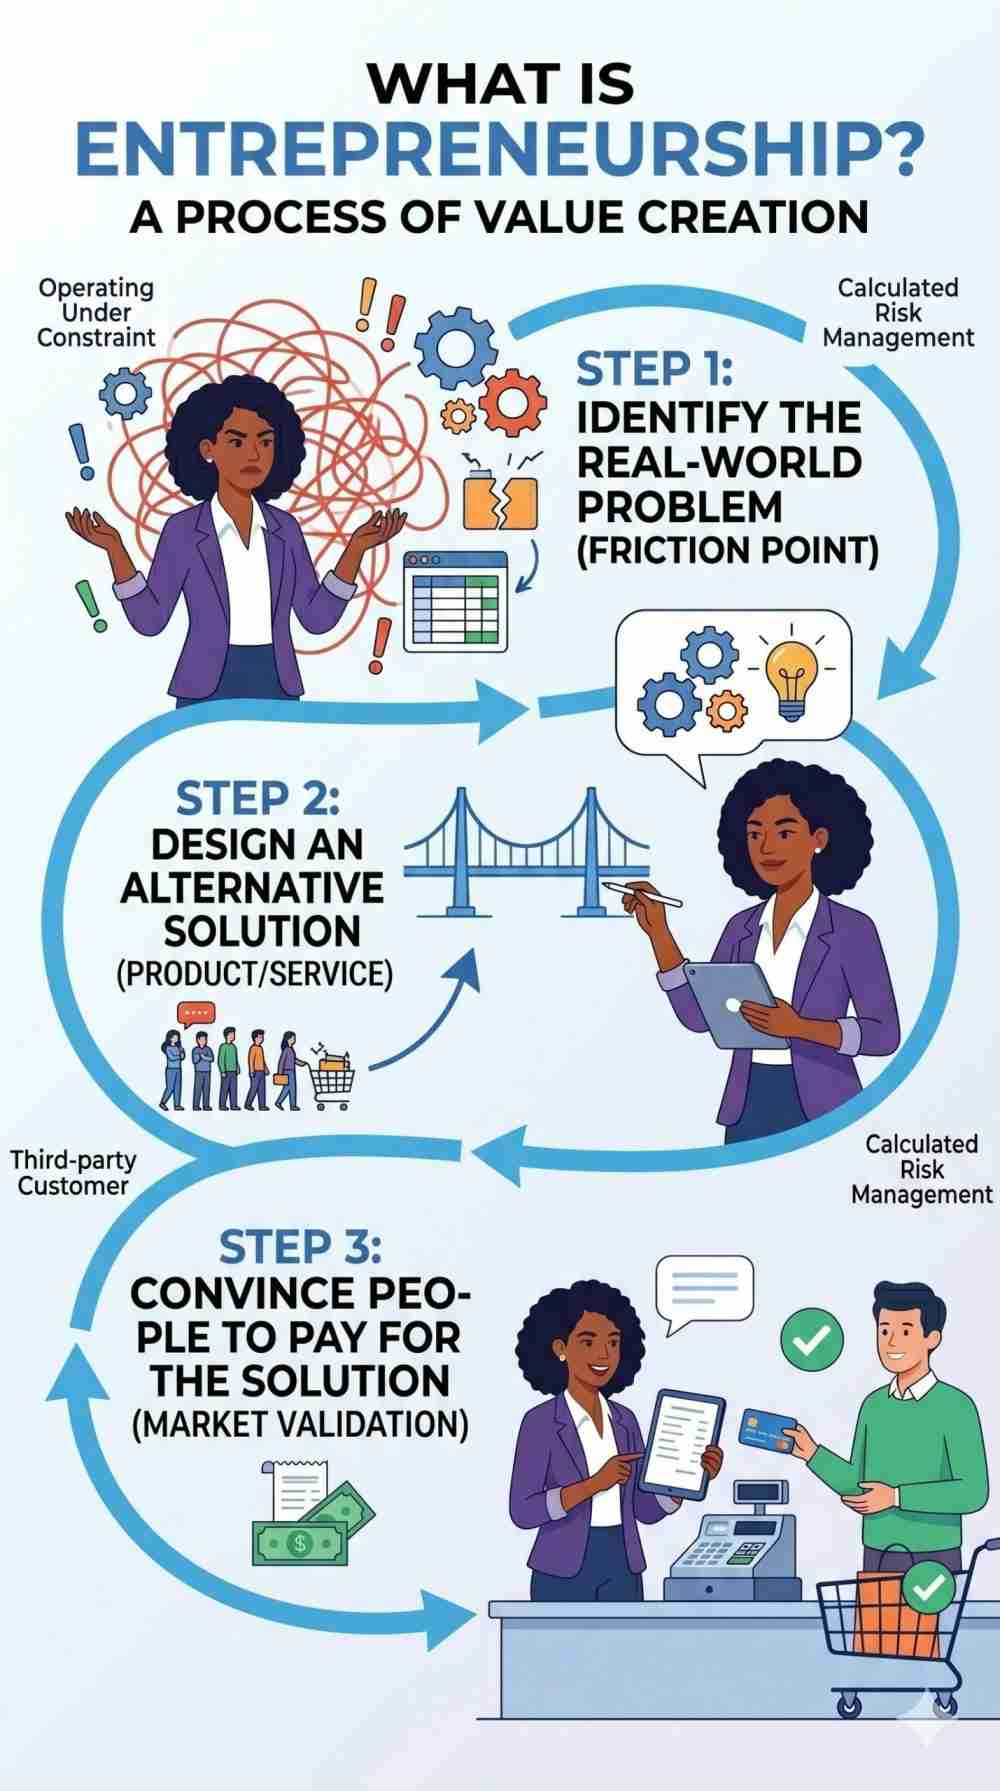
The definition used in business schools and educational institutions typically reads: "The ability and willingness to create, organize and run a business, as well as manage the inherent uncertainty."
While the above definition does provide an accurate representation of entrepreneurship, it does not consider the challenges and hardships found in everyday life.
Entrepreneurship in theory vs. reality
The textbook version of entrepreneurship states that an individual sees an opportunity, collects resources, and then creates value.
In reality, entrepreneurs observe other people's complaints regarding a particular software program, build an alternative solution in one weekend, have difficulties finding even one person to test it, have three users eventually sign up to be paying customers, and take two weeks to learn how to set up an account in Stripe to collect payment legally.
The real definition of entrepreneurship is about being able to operate and create value under constraint.
It is the ability to create value for society while navigating through uncertainty without needing permission to do so.
The relationship between problem solving and value creation
Money is a byproduct of creating value, not the purpose of the creation process.
If a business tries to make something that has no value to it, there will be no one to purchase its services or products.
Every business model that has achieved success originated from some form of friction point.
People dislike waiting in queues. Formatting financial reports is difficult for many individuals. Many companies use up resources on supply chains that are inefficient.
The entrepreneur's responsibility is to recognize the friction point, create a means of crossing over it, and charge a fee for doing so.
When charging a fee which is less than the cost of creating the original friction point, you have a sustainable business model.
The role of risk and uncertainty
Many people confuse risk with opportunity and often confuse the two as they both require an element of uncertainty associated with them.
Amateurs believe that entrepreneurship requires a "leap of faith" without knowing what the outcome will be.
Experienced entrepreneurs know that entrepreneurship is about managing risk by taking calculated risks.
You do not need to remortgage your home in order to validate an idea.
Instead, you can spend 100 EUR on targeted search ads to determine whether anyone clicks "Buy Now" from the landing page.
If they do, you collect their emails; if they do not, you pivot to a different strategy.
This is the basic premise of managing uncertainty. The goal of managing uncertainty is to make as many inexpensive mistakes as quickly as you can.
Types of entrepreneurship
Not every company is a technology company, and not all entrepreneurs aspire to be featured in newspapers or magazines.
The level of ambition and the scale of that ambition determines how you should run your business from the start.
Weekend side hustle
This is the first step to becoming an entrepreneur. You still maintain your regular job, but spend your evenings and weekends running a part-time business.
A side hustle is tailored for minimum overhead with maximum flexibility.
Your initial start-up costs can be minimal. The most difficult obstacle to overcome for people with two professional lives at the same time is time management and preventing burnout.
Solo proprietorship (Freelancer/Consultant)
This is the transition between a side hustle and full-time income. The business is YOU.
Freelance developers, independent consultants, and designers fall under this classification of business.
The barrier of entry is low, however, the scaling potential is limited. You can only trade so many hours for money.
You can increase your freelance rates, but you can never work more than 24 hours in a single day.
The main focus at this level is client retention and lead generation, as well as managing the variances of income on a monthly basis.
Small business ownership
Generally speaking, a small business refers to a localized or niche business that is designed to create a steady income stream, rather than just being hyper-growth driven.
A few examples of small businesses could include an independent coffee shop, a small boutique marketing agency, or a specialized plumber.
In general, the goal of establishing a small business is creating profit and a sustainable model.
These types of businesses require either startup capital to purchase equipment, pay lease costs, and hire initial employees.
The founders are building localized assets that provide service to the local community.
Scaleable startups
Scaleable startups are typically the business model that was created by Silicon Valley to promote rapid growth.
Typically, scaleable startups rely on a software or deep technology business model to enter the global marketplace.
These types of businesses are generally set up in order to lose money in the beginning stages, but are placing a greater emphasis on acquiring a large customer base before being profitable.
Opening a scaleable startup will typically require the assistance of outside funding, such as angel investing and venture funding.
Scaleable startups are extremely high-risk, extremely high-failure, but also have the potential to disrupt entire industries.
How to start your own company: A beginner's guide
The next step is turning your ideas into a business.
What does it mean to turn your ideas into a viable, profitable business that generates revenue? How do you turn your business idea into a successful business and make a living?
Starting your own business is not a simple process. Depending on how you approach starting your own company, you may miss steps in your preparation.
The following is a simple sequence of steps to help you get started.
Step 1 - Opening up the idea and improving the idea
The first thing you need to do is create a business idea.
In the beginning, most entrepreneurs will tell you to find something original and unique. However, this is not the most straightforward approach and can lead to much frustration in starting a business. Most successful businesses are just better, faster, or cheaper versions of existing products or services.
One of the most important things you can do is find a market where customers are already spending money, but that they have difficulty doing so.
Look for what customers are complaining about in reviews of popular products. Take a moment to listen to your coworkers complain about tasks they perform on a daily basis, and take note of their challenges.
The majority of the best ideas are ones that are boring.
What is meant by "boring" is an idea that has no excitement, but rather is practical. Practical ideas have the greatest chance of generating revenue.
Step 2 - Getting some validation of your idea before committing any financial resources
You should never create or produce anything without validating market demand.
While most entrepreneurs will tell you the first time they launch a product, they should get validation of their business idea from their friends, this is not good advice.
Your friends will most likely not tell you the truth about their opinions of your business idea for fear of hurting your feelings.
The only way to validate your idea is to ask someone you don't know very well to take out their wallet or purse to purchase your product.
Instead, what you should do is create a one-page website that clearly outlines your business and value proposition.
Place a pricing structure on the website. Drive a small amount of traffic to your website and see how many people attempt to make a purchase from your site.
If they try, then you have validation.
If no one makes a purchase, then you've just saved yourself six months of wasted time developing a product based upon a misconception about what your customers actually want.
This type of testing is known as a "smoke test", and is the way to separate real demand for your product or service from perceived demand.
The mapping of your micro-budget will be determined by the constraints of your capital.
If you only have a micro-budget of $/EUR 500 available to invest in your startup, you cannot squander that micro-budget on a highly expensive logo, a custom website or other impractical expenses that may jeopardize the success of your startup.
- You should allocate your micro-budget to the essentials.
- Your domain name will cost approximately $15.
- Basic webhost will cost approximately $50.
- Legal registration fee may cost between $100 to $200, depending upon your state or country.
After you have allocated these three expenses, the remainder of your micro-budget will be used to acquire customers through either hyper-targeted advertising or low-cost email software subscription services to reach out to customers.
You are going to use duct tape to this point. You will utilize free tools and perform all of the labor yourself.
Legal and operational problems
You cannot ignore the boring administrative aspects of running a business.
Before you can generate an income from your customers, you must understand the legal ramifications of operating your business.
To operate under the radar is one thing for a weekend's worth of work; however, when your business has paying customers, it is going to create significant financial liability for you personally.
You need to create a separate legal entity so that there is no longer any personal liability associated with your company's actions.
We will discuss this in further detail later, but the simple rule is that from day one of starting your business, treat it as if it were a separate entity from yourself.
Common pitfalls of new entrepreneurs
There have been countless failed businesses that all made the same predictable mistakes.
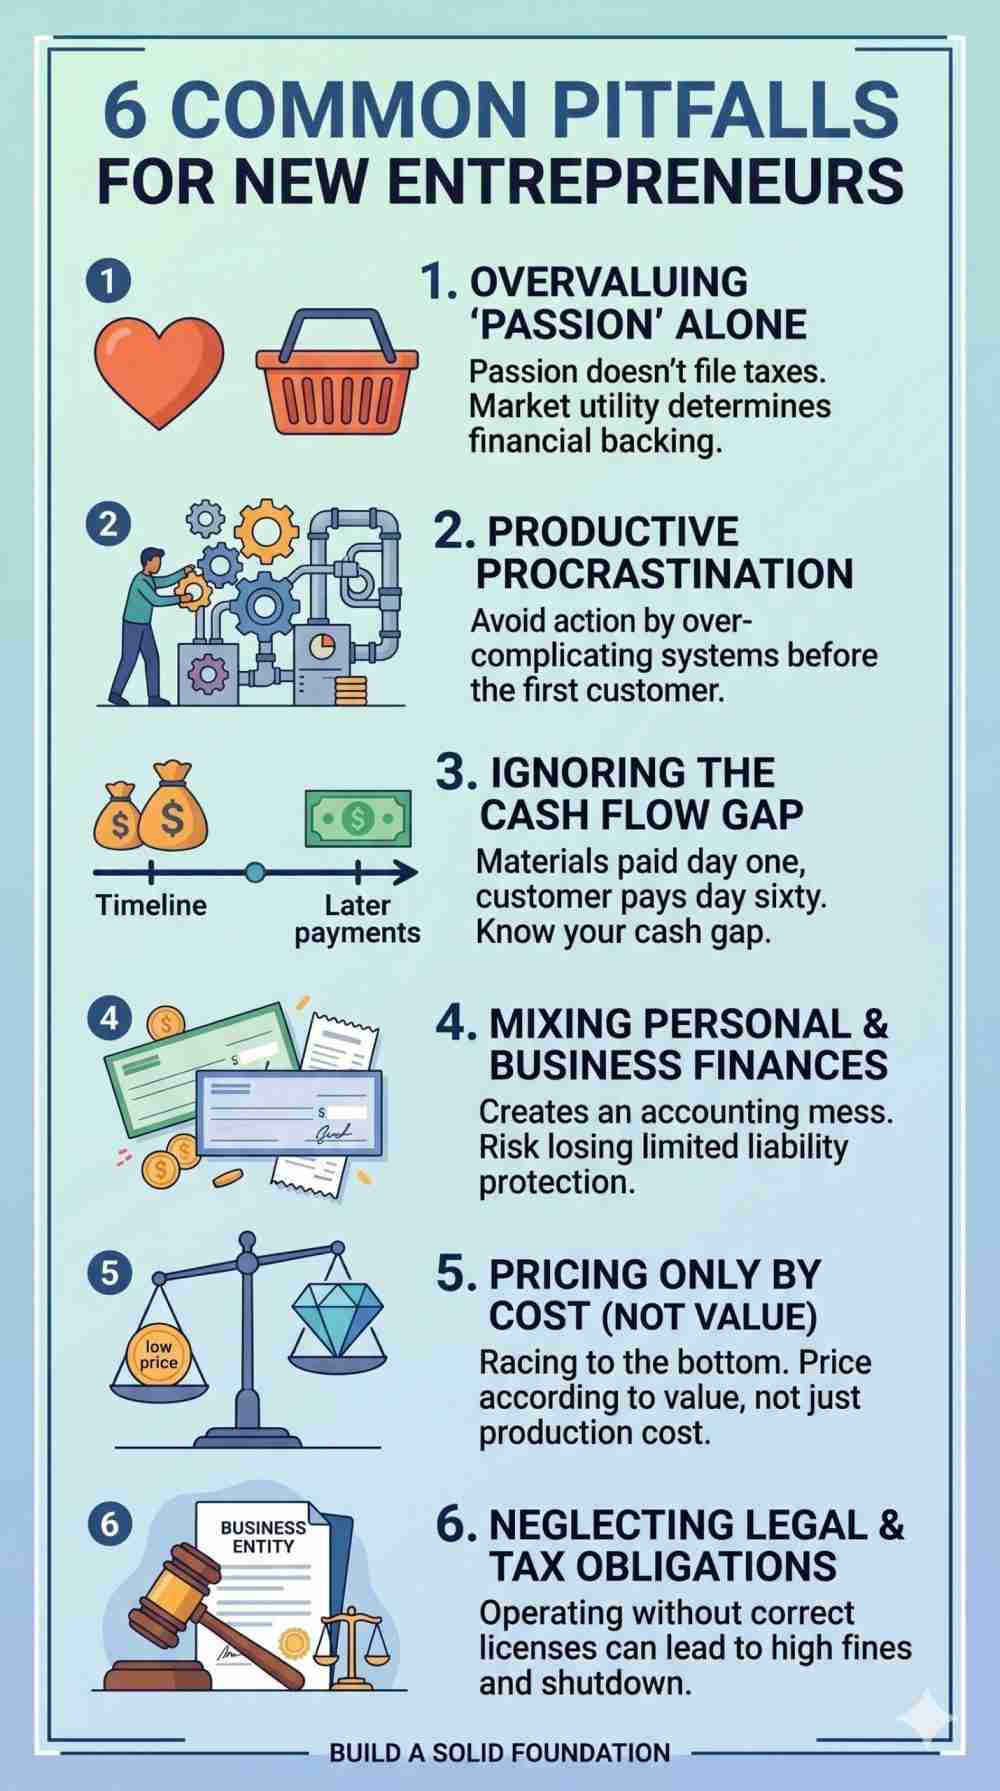
Recognizing these problems prior to starting your business is the most effective form of entrepreneurship.
Overvaluing "passion" as a business model
Passion will enable an entrepreneur to survive during difficult times, but it does not represent a viable business model.
For example, you may have a significant amount of passion for 14th-century pottery.
However, if the market for 14th-century pottery is relatively small, your business's ability to survive will be severely limited.
Your passion does not matter to the market.
The only thing that matters is how useful your venture is to a sufficiently large number of people to warrant financial backing.
In order to build a sustainable business that draws support from the marketplace, you must find that intersection where your passions intersect with the utility of a large enough number of people who are willing and able to financially support your business.
The road to success is paved with methodical approaches
Many beginners go down the path of trying to figure out how to design a system that can handle 10,000 users before they get their first customer.
This kind of thinking leads to what industry experts call "productive procrastination." You believe you are being productive and working towards your goal, yet in reality you are only avoiding taking action.
Do not purchase any inventory for your business for a whole year.
Do not automate any processes until you have a proven track record for doing all of them manually. Do things that cannot be scaled out or automated in the beginning.
Hand-write emails to your first ten customers. Manually fulfill all the first twenty orders that are placed with you.
Make sure that you spend the appropriate amount of time getting to know and understand the entire process of your business very well at a personal level before you at least try to automate it.
Understanding cash flow is critical when starting a business
Profit is a concept. Cash flow is a reality.
You can run a profitable business on paper and still go bankrupt when your cash is tied up in unbroken inventories or unpaid invoices.
Therefore, you need to know when your suppliers want to be paid, when your customers will be paying you, and when you will have the cash available to pay your suppliers.
If you pay for materials on day one, yet your customer does not pay you until day sixty, then you have a 59-day cash gap.
Knowing how to manage that cash gap will become the "heartbeat" of every successful business operation.
Business formation and settings for business operations
As soon as you begin the process of converting an idea to a business, you expose yourself to a multitude of legal structures, tax obligations, and liability profiles.
Failure to establish these things correctly puts you at risk. If you establish your business properly, it creates an additional layer of protection for your personal assets.
Sole proprietorship & standard corporation / limited company
When you begin doing business and do not file any paperwork, you are considered a sole proprietor by default.
This is the easiest pathway, but the most dangerous too. As a sole proprietor, there is no legal separation between you and the business entity.
As a result, should your business become involved in litigation or your business default on a debt obligation, the courts can easily access all your personal assets, including but not limited to, your savings, car, house, etc.
Once you have formed and registered a limited liability company (LLC) in the U.S. or a private limited company (LTD) in Europe and the UK, a firewall has been established.
The LLC is now a separate and unique legal entity that will protect your personal assets should the business entity fail.
Establishing an LLC or Ltd does have a small fee associated with it and requires the entity to file an annual report. However, the minimal investment is well worth the protection it offers.
Establishing your business financial infrastructure
There are absolutely no circumstances under which you should ever run any business expenses utilizing your personal checking account.
Mixing personal and business funds will create a significant accounting mess and run the risk of "piercing the corporate veil", which means losing the liability protections of your LLC or LTD.
After registration of your business entity, the very first operational task is to establish a separate business banking account.
To keep track of all your revenue, make sure every dollar of revenue goes into a specific bank account. Similarly, use the same bank account to pay all business expenses.
Begin immediately using accounting software to track revenue and expenses.
You do not need an expensive accountant for at least the first three months of your business. However, you do need to maintain accurate, organized records during this time.
Licensing and taxes
Please remember that the government wants its fair share of the business profits.
Depending on where you are located and what kind of business you operate, you may owe more than one type of tax: sales tax, VAT, self-employment tax, or corporate tax.
Start putting aside tax money as soon as you begin selling your products or services and do not wait until the end of the year to figure out how much tax money you will need to pay.
A good rule of thumb is to put aside 20%-30% of your total sales into a separate tax savings account.
You should also understand that you will not be able to keep all of this money; the government takes a percentage.
In addition to taxes, be sure you know what the local licensing requirements are before you start operating your business.
For example, a digital marketing agency only needs a basic business license; whereas, a home-cook food business must pass health department inspections and meet the requirements for obtaining specialized permits.
Operating a business without the correct licenses can lead to very high fines and being shut down immediately.
Getting your first customer
You have your idea. You formed an LLC. You opened a bank account.
Now you must generate revenue.
The most difficult part of being an entrepreneur is acquiring customers. This is where the true marketer separates themselves from the "idea" people.
Beyond friends and family
Having your mom buy your product does not constitute market research. Signing up for your service by your former college roommate is not considered a sale but rather a favor.
A true validation of an offer occurs when an objective third party encounters an offer, evaluates the price of the offer against the value of the offer, and decides to purchase the offer.
In order to reach these objective third-party validators, you must go to where they congregate.
If your offer is for a software as a service (B2B), then you must be doing cold outreach on LinkedIn, or by going to trade shows related to the industry of your offer.
If your offer is for consumer-type products, then you must master the art of targeting social media ads or building an organic community.
30-day customer challenge
Establish a brutal constraint; for the next 30 days, you have to acquire a paying customer that is a stranger to you.
This will force you to stop tweaking the logo and to start selling. It forces you to send out the cold emails that you have been avoiding sending.
Expect to receive rejection. For every 100 emails, you will most likely receive 99 ignored emails and one angry reply.
And then you will send another 100 emails. Sales is a numbers game, and the quality of your targeting will greatly influence the outcome.
The goal of your first 30 days is not to be profitable; it is to show that the mechanism you have created is capable of converting a stranger into a buyer.
Pricing for reality, not ego
Newcomers generally underprice their products/services. Newcomers think that having the lowest price gives them a competitive advantage.
Usually, competing only on price leads to a race to the bottom.
Companies that compete only on price will attract the most demanding, least loyal customers. The low price margin will prevent you from investing in marketing or product enhancement.
Price according to the value your offering provides to the customer, not by what it costs you to create.
If you can deliver a software solution that saves a company ten hours of payroll per week worth $500, it makes zero difference whether you spent $2 to host the software; you should charge $50 per month.
A software package that saves companies time and money is worth significantly more than what you spend to own or create it.
Is entrepreneuring your future? Decision matrix
Not everyone possesses the appropriate mindset for that type of entrepreneur.

Although the media glamorizes the hustle of working towards success, the reality of entrepreneurship is full of stress and isolation while juggling constant demands for problem-solving capacity.
The first step in determining whether or not to become an entrepreneur is to perform a brutal self-check of your situation.
Time and capital assessment
Do you have a runway? How many months will your current job allow you to pay rent when the new venture starts?
If the answer is less than six months after quitting, do not quit your job. Start building the business as a side hustle.
Taking the risk of creating an entrepreneurial venture while facing an eviction leads to bad choices. You will likely hire poor clients, cut your prices, and act out of desperation.
Sufficient capital to make strategic, long-term decisions will give you time to build the business properly.
Assess your available weekly hours objectively. If you cannot find 15-20 hours a week to focus solely on your startup, the venture will likely become stalled.
Tolerance for undefined spaces
When you accept a traditional position, your superior provides you with a plan to follow. If you follow that plan, you receive compensation.
When you are an entrepreneur, there is no plan provided by a superior. You must create a plan, create your own road, and operate your vehicle simultaneously.
You will wake up on Tuesday, not knowing whether your marketing efforts will have a successful outcome, whether your customer will pay their invoice on time, or whether your website will experience an outage.
If unawareness paralyzes you, the challenges of entrepreneurship will be excruciating.
You will need to have the ability to develop psychological resilience that will aid you in making decisions with only 70% of the data available to you.
You will need to act on the initial 70% of data and make adjustments while executing your plan.
The last word on the entrepreneurial journey
Starting a business will create a higher level of forced self-growth than anything you could possibly experience.
Starting and running a business will eliminate all of your excuses. You will be forced to address your inefficiencies. The market rewards outcomes, not good intentions.
To be successful as an entrepreneur, you will need both cynical realism and persistent execution.
You need a cynical mindset that will allow you to identify your own weaknesses, protect yourself from liabilities, and stay on top of your cash flow.
You will also need relentless willpower to overcome the rejections, failures, and complete loss of faith that are sure to occur during the startup process.
Entrepreneurship is not the lottery; it is hard work!
However, once you master the mechanics of entrepreneurship, you will gain a certain amount of independence, control of your finances, and everything else that comes with being in charge of your own business.
You must first build the foundation for your business, validate the need, protect your liability, and start building your business.
Frequently Asked Questions (FAQs)
What is the hardest part of starting a business?
The biggest hurdle in beginning a new company is often the gap between product creation and consumer sales, or Customer Acquisition.
Founders are typically great at creating their products but struggle with selling them.
Many entrepreneurs face the biggest challenges in sales/marketing primarily due to their fear of being rejected and not knowing how to execute successfully in those areas.
Do I need to create a formal business plan to launch my business?
No, formal Business Plans of approx. 50 pages are now generally not necessary or effective for bootstrapping entrepreneurs.
Unless you are going to a traditional bank for a loan or seeking to raise Venture Capital (VC) funding, you will likely be better served by creating a "Lean Canvas"; which is essentially a one-page document that describes your target market, value proposition, cost structure and revenue model. Validation always wins over documentation.
How much money do I need to start a small business?
This is very model-dependent.
If you're going to start a Service-Based (Freelance) business or a Digital Product side business, then you could potentially start your business for less than a few hundred dollars for domain names, hosting and legal registration fees.
However, if you plan to create a product-based retail company, an in-store retail location or a deep-tech Software-as-a-Service company, you're likely going to need significantly more capital.
Always try to use the least amount of money required (minimal costs) to validate your business idea before you invest substantial money into it.
Can I keep my full-time job and start a business?
Yes. In fact, I would highly encourage doing this.
If you are working a full-time job, there is no pressure on you to make your business pay your rent on month 1, and focusing on your business full-time allows you plenty of time to manage both while you test whether or not your business idea is going to succeed.
